The Great Gratuity Shift: How America’s Restaurant Economics Are Rewriting Dining Culture

The Numbers Behind the Napkins

The American restaurant industry generated over one trillion dollars in revenue last year alone. But here’s what blows my mind: despite feeding millions daily and employing massive networks of workers, restaurants run on margins so thin they’d make a paper manufacturer jealous. We’re talking three to nine percent across all categories.
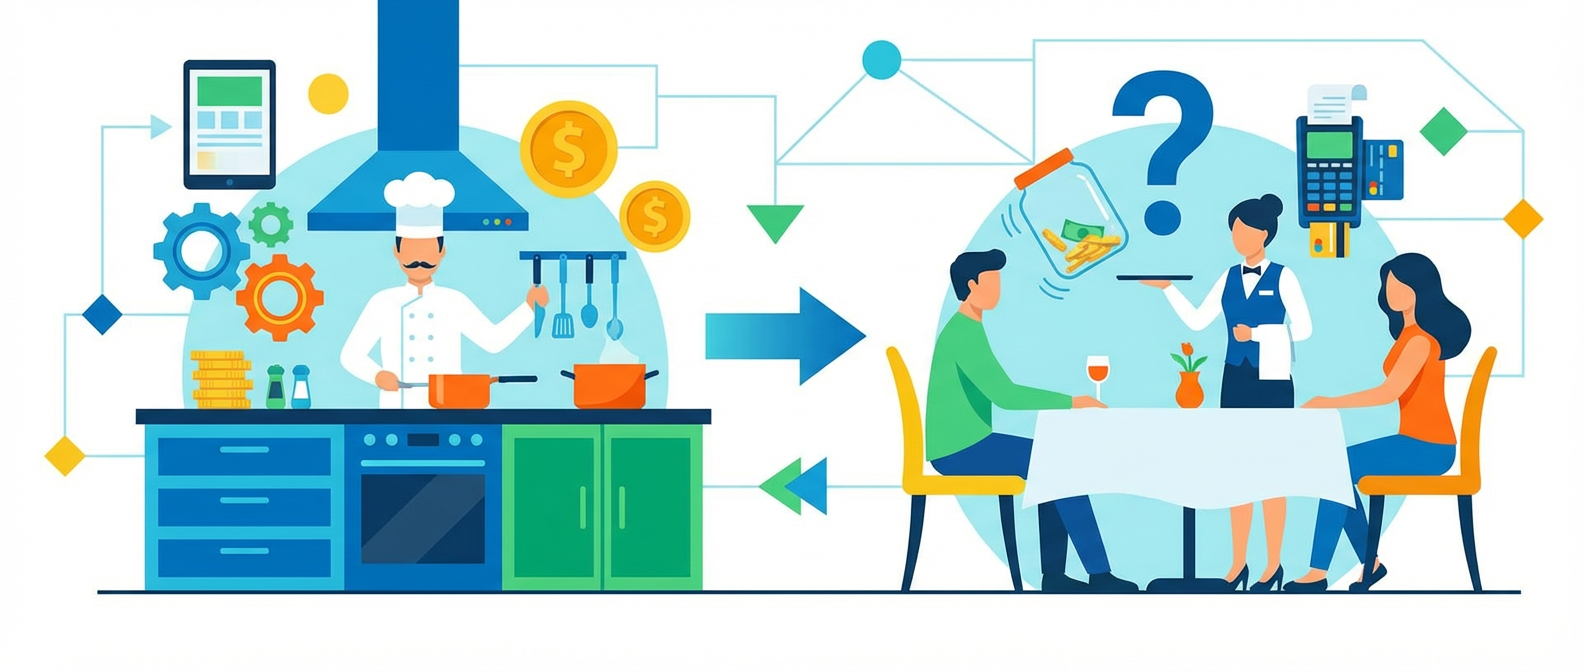
The Great Gratuity Shift: How America's Restaurant Economics Are Rewriting Dining Culture
The Great Gratuity Shift: How America’s Restaurant Economics Are Rewriting Dining Culture

This reality creates a fragile ecosystem where every penny counts. Retail businesses might enjoy margins of twenty percent or higher, but restaurants juggle food costs, labor expenses, and rent pressures while trying to maintain quality. The National Restaurant Association tracks how these razor-thin margins force operators into impossible choices about pricing, staffing, and staying afloat.

The industry’s growth reflects how much our relationship with food has changed. What used to be about simple sustenance now doubles as entertainment, social currency, and cultural expression. But this transformation creates economic tensions that show up in every transaction, from kitchen prep to your final bill.
Illustration for The Great Gratuity Shift: How America's Restaurant Economics Are Rewriting Dining Culture
Illustration for The Great Gratuity Shift: How America’s Restaurant Economics Are Rewriting Dining Culture

The Cultural Weight of the Tip Jar

Tipping culture in America goes way deeper than just money changing hands. We borrowed it from European aristocratic traditions, but it evolved into something uniquely American, woven into our social fabric. Now survey data shows three-quarters of customers feel pressured when they see those tipping prompts. Researchers actually have a name for it: “tipping fatigue.”

This fatigue isn’t just about annoyance. It signals a real shift in how Americans think about fairness, transparency, and what we owe each other when dining out. Digital payment systems made it worse by turning what used to be a private decision into a public performance. Now we face tipping screens for coffee, takeout orders, pretty much everything beyond traditional table service.

The constant pressure to calculate appropriate tips turns fun experiences stressful. Diners tell researchers they feel uncertain about proper amounts, guilty about seeming cheap, and frustrated by unclear expectations. What should be simple transactions become awkward social negotiations that affect where and how often people eat out.

Service-Included: Learning from Global Traditions

Some forward-thinking restaurants in coastal cities are ditching tips entirely with service-included pricing models. They build service charges directly into menu prices, like they do across Europe, Australia, and parts of Asia. The transparency appeals to customers and gives workers stable income.

This shift runs deeper than economics though. These restaurants are importing cultural practices from societies where hospitality operates differently. In France or Japan, exceptional service is just professional standard, not something requiring extra payment. This challenges core American beliefs about motivation, fairness, and how service quality relates to money.

Early results are mixed. Many customers love the transparency and freedom from tipping anxiety, but others balk at higher menu prices even when total costs stay the same. Success often depends on clear communication about the change and education about global dining norms. Eater food culture reports suggest younger diners adapt more easily, while older customers sometimes see it as pretentious European nonsense.

Digital Disruption and the Commission Conundrum

Food delivery platforms created new economic pressures that complicate restaurant math even further. These digital middlemen take twenty-five to thirty-five percent of each order as commission, crushing establishments already running on minimal margins. It’s a fundamental shift in how restaurants reach customers and manage revenue.

Culturally, delivery platforms changed what restaurant dining even means. They separated food from atmosphere, service, and social experience that traditionally defined restaurant culture. This unbundling creates new realities where restaurants basically run multiple businesses: the traditional dine-in experience and the delivery-optimized kitchen.

The commission structure forces impossible choices. Restaurants can absorb costs and kill their already slim profits, raise delivery menu prices, or try pushing customers toward direct ordering systems. Each option carries risks and reflects bigger questions about restaurant culture’s future in an increasingly digital world.

The Ghost Kitchen Experiment and Cultural Evolution

The pandemic sparked explosive growth in ghost kitchens, delivery-only operations that promised to revolutionize restaurant economics by cutting front-of-house costs and expensive real estate. These ventures attracted massive investment as entrepreneurs imagined a future where food production could be optimized purely for delivery efficiency without traditional dining’s cultural baggage.

But as pandemic restrictions lifted, the ghost kitchen boom crashed hard. This retreat reveals something important about human dining behavior that purely economic models missed. Even with convenience and often lower prices, consumers consistently prefer restaurants that offer complete cultural experiences rather than just food delivery.

The ghost kitchen experiment shows the limits of treating food service as purely transactional. These operations excel at satisfying hunger efficiently but struggle to replicate the social, aesthetic, and emotional elements that make dining memorable. This cultural dimension proves remarkably resistant to economic pressure, suggesting restaurants provide value beyond nutrition that customers willingly pay to preserve.

Restaurant economics and tipping culture keep evolving as operators, workers, and customers balance competing pressures of fairness, tradition, and financial survival. These changes reflect broader shifts in American work culture, social expectations, and our relationship with service industries. What emerges from this mess will probably reshape how we dine for decades.
Beyond the Burger: How Plant-Based Food Is Outgrowing Its Own Hype

The Great Pivot From Meat Mimicry

The plant-based food revolution has reached a turning point. After years of chasing perfect meat replicas, the industry is figuring out something interesting: consumers don’t just want fake meat that bleeds. They want real food that happens to be plants.

Beyond the Burger: How Plant-Based Food Is Outgrowing Its Own Hype

This shift is obvious when you look at the numbers. Companies like Beyond Meat and Impossible Foods, once the darlings of the alternative protein world, have watched their revenues drop off significantly since their pandemic highs. But here’s what’s actually happening in restaurant kitchens and home pantries across America. Chefs are getting excited about tempeh’s nutty complexity, jackfruit’s weird but wonderful texture, and bean-heavy dishes that show off their plant origins instead of hiding them.

The science behind this change explains why mimicry was always a bridge, not the final destination. When food technologists first went after plant-based alternatives, they focused on copying the sensory experience of meat through isolated proteins, methylcellulose, and heme compounds. These innovations did their job, introducing regular consumers to the idea that plants could satisfy meat cravings. But as people’s tastes grew, so did their expectations.

The Flexitarian Majority Takes Center Stage

The biggest change in plant-based eating isn’t happening among vegans or vegetarians. It’s happening with flexitarians, who now make up 36 percent of American dietary identities. That makes them the largest single group. These consumers approach plant foods without the ideology, looking for variety, health benefits, and environmental benefits rather than perfect meat copycats.

This demographic shift explains why whole food plant-based eating keeps growing while ultra-processed alternatives have hit a wall. Flexitarians love lentil walnut bolognese not because it tastes like ground beef, but because it delivers rich umami flavors and satisfying textures on its own terms. They pick mushroom-based proteins for their earthy depth and nutrition, not their ability to trick anyone into thinking they’re eating animal products.

The cooking world is responding. Fine dining restaurants now build menus around what plants actually do well. Fermented black garlic adds serious complexity to vegetable dishes. Koji transforms grains into deeply savory ingredients. These techniques don’t hide behind meat comparisons. They show off what plants can do when treated with respect and creativity.

Precision Fermentation Rewrites the Rulebook

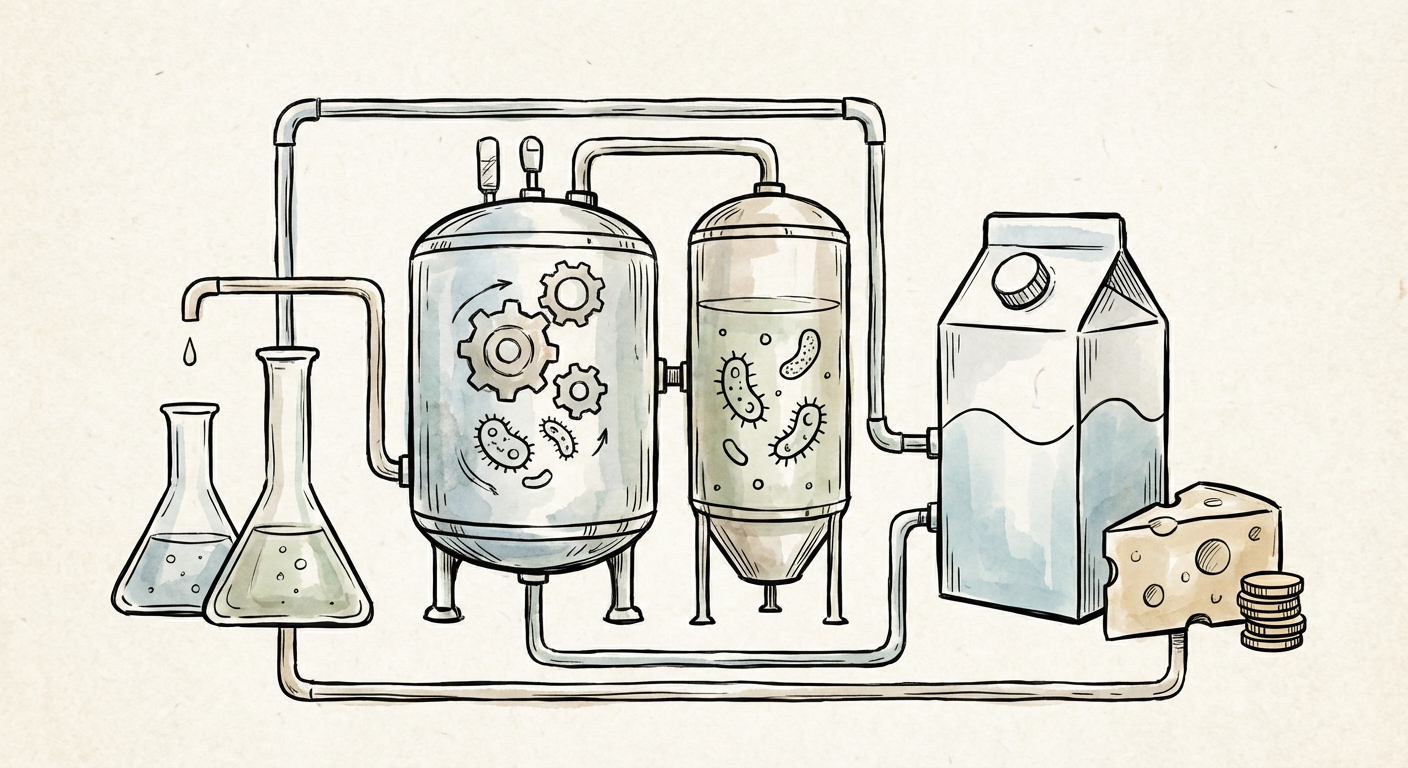
While consumer preferences drive cultural change, tech breakthroughs make structural transformation possible. Precision fermentation is the biggest advancement in alternative proteins since the first plant-based burger hit grocery shelves. This process uses microorganisms to produce animal proteins without animals, creating dairy components that are molecularly identical to conventional ones.

The possibilities go way beyond replacing cow’s milk. Precision fermentation can produce casein proteins for cheese that melts and stretches properly, whey proteins for baking, and even more specialized proteins like egg whites or collagen. Good Food Institute research shows these technologies are getting close to cost parity with conventional dairy proteins, which could revolutionize entire food categories.

Unlike earlier plant-based innovations that needed extensive processing to approximate animal products, precision fermentation creates the actual proteins consumers expect. A cheese made with fermentation-derived casein doesn’t compromise on function or taste. It just removes the cow from the equation while keeping the molecular structure that makes cheese behave like cheese.

Institutional Adoption Signals Mainstream Acceptance

The best indicator of how plant-based food is evolving shows up in institutional settings where practical concerns matter more than trends. School districts across California and New York are expanding plant-based lunch programs, driven by cost savings, nutrition requirements, and environmental goals. These institutions don’t chase viral food moments. They respond to proven value and real demand.

This institutional embrace reflects how the market has grown up. Early adopters have moved past novelty seeking toward actually integrating plant foods into their regular eating patterns. Food Navigator plant-based coverage consistently shows this pattern: initial excitement about meat substitutes followed by steady growth in diverse plant-forward options.

School cafeterias really show this evolution. Students don’t need their black bean burgers to bleed or their cashew cheese to perfectly copy dairy. They need food that tastes good, provides proper nutrition, and fits the budget. When plant-based options meet these practical requirements, adoption happens naturally.

The Science of Satisfaction Beyond Simulation

Understanding why plant foods work when they stop trying to be something else requires looking at the neuroscience of eating satisfaction. Our brains process food through multiple channels: taste, smell, texture, how it looks, and even sound. Early meat alternatives focused heavily on looking right and basic taste matching while ignoring other important elements.

Modern plant-based development takes a bigger picture approach. Tempeh’s fermentation creates complex flavor compounds that hit umami receptors without needing meat flavoring. Properly prepared jackfruit provides fibrous textures that feel substantial and satisfying. Bean-based dishes offer protein density and mineral content that support satiety signals.

This scientific understanding explains why whole food approaches often beat highly processed alternatives in consumer satisfaction studies. When plant ingredients are prepared using traditional fermentation, proper seasoning, and appropriate cooking techniques, they create their own compelling sensory experiences rather than copying others.

The future of plant-based eating isn’t about perfect simulation but about showing what plants can actually do. As precision fermentation technologies mature and cooking techniques evolve, we’re seeing the emergence of a food system that celebrates plant diversity while meeting practical needs for nutrition, sustainability, and pleasure. This evolution suggests that the most successful plant-based foods won’t be the ones that best copy animal products, but those that most fully realize what plants can be.

Beyond the Hype: How Plant-Based Dining Outgrew Its Own Marketing Machine

The Meat Alternative Bubble Deflates

The meteoric rise of companies like Beyond Meat and Impossible Foods captured headlines and investor dollars, but their recent revenue declines tell a more complex story about where plant-based eating is actually headed. After reaching pandemic-era peaks when home cooking dominated, sales of these heavily marketed meat substitutes have stumbled as consumers returned to restaurants and reassessed their priorities.

This wasn’t just a post-pandemic correction. The decline shows a fundamental shift in how people approach plant-based eating. Early adopters who jumped on the bandwagon for novelty have moved on, while those committed to reducing meat consumption have evolved beyond simple substitution. The result is a more mature market that demands authenticity over marketing buzz.

Restaurant operators watched this transition firsthand. Initial enthusiasm for impossible burgers and beyond sausages gave way to customer fatigue with processed alternatives that often cost more than their animal counterparts while delivering inconsistent results. Smart kitchens began pivoting away from these products before the financial reports confirmed what dining rooms already knew.

Whole Foods Win Where Processing Fails

While ultra-processed plant alternatives plateau, whole food plant-based eating continues its steady climb. This isn’t about replacing meat with laboratory-crafted lookalikes. Instead, it celebrates vegetables, legumes, grains, and fruits on their own terms. The approach resonates with diners who want transparency in their food sourcing and preparation.

The Good Food Institute research supports this trend, showing sustained growth in minimally processed plant options even as heavily engineered alternatives lose momentum. Restaurants find these ingredients more reliable to work with, offer better margins, and create more distinctive menu items that can’t be replicated at home with a quick grocery store run.

This shift reflects broader consumer skepticism about food processing. After years of clean eating trends, many diners view highly processed plant-based meats with the same wariness they reserve for conventional processed foods. The irony is obvious: products marketed as healthier alternatives face rejection for the very processing that makes them possible.

Fine Dining Embraces Plant-Forward Innovation

High-end restaurants have largely abandoned meat analogues in favor of ingredients like tempeh, jackfruit, and creative legume preparations. These kitchens understand that sophisticated diners want innovation, not imitation. A perfectly prepared piece of jackfruit or a house-made tempeh can command premium prices while showing culinary skill in ways that reheating a Beyond patty never could.

This evolution benefits both restaurants and customers. Chefs gain creative freedom to develop signature preparations using traditional fermentation techniques or modern vegetable cookery. Diners experience genuinely unique flavors and textures that don’t invite comparison to animal products. The result is plant-based dining that stands on its own merits rather than attempting to fool anyone.

Menu development in this space requires actual culinary expertise rather than vendor relationships. Restaurants that master these techniques differentiate themselves meaningfully from competitors still relying on manufactured solutions. The learning curve is steeper, but the payoff includes better food costs, unique offerings, and the ability to adapt quickly to changing supplier dynamics.

The Flexitarian Majority Drives Practical Change

Perhaps most importantly, flexitarians now represent the largest dietary identity in America at 36 percent of consumers. These aren’t committed vegetarians or vegans, but people actively reducing meat consumption without eliminating it entirely. This massive demographic shift has serious implications for restaurant strategy and menu development.

Flexitarian diners approach plant-based options differently than committed herbivores. They’re less tolerant of subpar meat substitutes because they have easy access to the real thing. They prioritize flavor, value, and satisfaction over ideological purity. This demands a different approach to plant-based menu development focused on deliciousness rather than dietary accommodation.

Smart restaurants now design plant-forward dishes that appeal to flexitarians without alienating omnivores. This might mean a mushroom and grain bowl that satisfies on its own terms, or a vegetable-centric pasta that doesn’t need cheese or meat to feel complete. The goal is inclusivity rather than substitution, creating options that work for diverse dining groups.

Technology Enables Authentic Alternatives

While consumer-facing meat alternatives struggle, behind-the-scenes innovations show more promise. Precision fermentation technology now produces animal-free dairy proteins at costs approaching conventional dairy. Unlike highly processed meat substitutes, these proteins can enhance familiar preparations without calling attention to their plant origins.

This technology matters more for food service applications than retail products. Restaurants can incorporate these proteins into existing recipes for cheese sauces, desserts, and baked goods without major menu changes or staff retraining. The innovation stays in the background, improving functionality and reducing costs rather than demanding customer buy-in to new categories.

Institutional food service shows particular promise for these applications. School lunch programs across California and New York are expanding plant-based offerings, creating stable demand for ingredients that work within existing preparation methods and equipment. Food Navigator plant-based coverage highlights how these programs prioritize nutrition and familiarity over novelty, creating sustainable adoption patterns.

The future of plant-based dining lies not in replacing traditional restaurant categories, but in expanding them. As the industry matures beyond initial hype cycles, successful operators will focus on ingredients, techniques, and preparations that enhance their overall offerings rather than creating separate plant-based silos. This evolution promises better food, more sustainable operations, and dining experiences that satisfy the growing number of customers seeking delicious options that happen to be plant-based.

What Seasonal and local food advocacy Reveals About Plant-based food evolution past the hype

When you really dig into the evidence, it tells a much more specific story. Plant-based food evolution past the hype deserves better attention than most typical coverage gives it, and honestly, the reason isn’t that complicated once you know where to look.

The data worth focusing on isn’t the headline number. What’s really happening is whole food plant-based eating is growing while ultra-processed alternatives are plateauing. That’s the more grounded read of the situation, and it’s also more accurate once you examine what the evidence actually shows.

The Advocacy: Setting the Terms

Beyond Meat and Impossible Foods revenue declining after their pandemic peak isn’t just a data point in plant-based food evolution past the hype. It’s the structural condition that makes everything else in this analysis make sense. This kind of context doesn’t age quickly. The conditions that produced it have been building for years, and their convergence makes this moment different from previous ones that looked similar from a distance.

You’ve got whole food plant-based eating growing while ultra-processed alternatives plateau, plus tempeh, jackfruit, and legume-forward menus replacing meat analogues in fine dining. Look at both together and a pattern emerges that Good Food Institute research has been covering from the inside. The conditions are more durable than they first appear, and the implications go further than the immediate headlines suggest.

To understand why this matters, compare what was true three years ago to what’s true now. The difference isn’t simply quantitative, it’s qualitative. The participants, infrastructure, and incentive structures have all shifted in ways that build on each other rather than cancel out. That compounding effect is the most important element to track.

What makes this moment worth examining carefully isn’t the novelty but the confirmation. The underlying dynamics have been visible for some time. What’s new is that they’ve reached a threshold where ignoring them requires active effort rather than simple inattention. That threshold crossing is the real event, not the underlying movement that produced it.

And the flexitarian category becoming the largest dietary identity in the US at 36 percent is part of that same picture. These elements don’t exist in separate silos. They’re reinforcing conditions in the same structural shift.

The Seasonal Argument: The Analysis

The flexitarian category becoming the largest dietary identity in the US at 36 percent is where the analysis gets more specific. The surface reading is accessible and not wrong, but it misses the mechanism. And the mechanism is where the practical insight lives. The data worth focusing on isn’t the headline number but the mechanism: precision fermentation enabling animal-free dairy proteins at competitive cost. Understanding it changes what you do with the information.

Consider what precision fermentation enabling animal-free dairy proteins at competitive cost actually represents in context. It’s not a correlation that happened to appear. It’s a downstream consequence of structural factors that have been compounding. Previous readings of similar situations failed because they treated the symptom as the cause. The structural account is less satisfying as a headline but more useful as an analytical tool.

The comparison to prior cycles is instructive precisely because of where it breaks down. Superficially similar conditions resolved differently in previous iterations because the substrate was different. School lunch plant-based programs expanding across California and New York represents a substrate change, the kind that alters how elastic the system is rather than just its current value. Recognizing that distinction separates analysis from pattern-matching.

The skeptical counterargument deserves honest engagement: prior moments with similar surface characteristics didn’t produce the outcomes that seemed logical at the time. That history is real. What’s different now is school lunch plant-based programs expanding across California and New York, which isn’t a minor variable. It’s the infrastructure condition that previous cycles lacked. Infrastructure changes tend to be persistent in ways that sentiment-driven changes aren’t. Food Navigator plant-based is one source tracking this dimension with the rigor it requires.

There’s also a distributional question that often goes unaddressed in coverage of plant-based food evolution past the hype: who captures the value created by these shifts, and who absorbs the disruption costs? The aggregate picture can be positive while the distribution is uneven in ways that matter enormously to specific participants. Keeping that distributional lens in view is part of reading the situation clearly rather than simply optimistically.

Implications: What This Means If You Care About Seasonal eating

The implications of plant-based food evolution past the hype extend beyond the immediate context. Beyond Meat and Impossible Foods revenue declining after their pandemic peak, combined with the structural conditions described above, creates a situation where adjacent fields, decisions, and communities get affected in ways that aren’t always visible from inside the primary story. The second-order effects are frequently more important than the first-order ones, and they’re where careful attention pays the highest returns.

Here’s where the analysis departs from mainstream coverage: tempeh, jackfruit, and legume-forward menus replacing meat analogues in fine dining is a leading indicator rather than a lagging one. The people positioned to respond to what this signals, rather than to what it confirms, are the ones who will be less surprised by what follows.

The practical response depends heavily on your position relative to these dynamics. For those closest to the core of plant-based food evolution past the hype, the implications are immediate and operational. For those at greater distance, the implications are strategic, a matter of understanding which adjacent pressures are building and which assumed stabilities are more fragile than they appear.

The practical question isn’t whether to engage with these dynamics but how. The answer depends on context, on what role you occupy relative to plant-based food evolution past the hype and what your actual decision horizon is. But the first step is the same regardless: accurate understanding of what’s actually happening rather than what the most available narrative says is happening.

A few concrete observations are worth separating out from the broader analysis. First: whole food plant-based eating growing while ultra-processed alternatives plateau isn’t a temporary condition, it’s a new baseline. Second: precision fermentation enabling animal-free dairy proteins at competitive cost suggests that the adjustment period isn’t over. Third, and most important: the organizations and individuals who are treating the current moment as a new steady state rather than a transition are making a categorization error that will be costly to unwind later.

The Case Against: What the Critics Get Right

Intellectual honesty requires acknowledging the strongest counterarguments, not just the weakest ones. The case against the optimistic reading of plant-based food evolution past the hype isn’t trivial. There are structural vulnerabilities in the current picture that deserve direct engagement rather than dismissal.

The most serious objection is about sustainability. Tempeh, jackfruit, and legume-forward menus replacing meat analogues in fine dining can be read not as a foundation but as a ceiling, a point beyond which growth becomes self-limiting because of the very dynamics that produced it. If the current state has already incorporated most of the available supply of early-adopting participants, the remaining growth curve may be structurally shallower than the recent trajectory implies.

There’s also the policy and regulatory dimension. Beyond Meat and Impossible Foods revenue declining after their pandemic peak describes a condition in a relatively permissive environment. Regulatory responses to the scale implied by these numbers aren’t inevitable, but they aren’t implausible either. The organizations that are planning as though the current regulatory environment is permanent are making an assumption that the history of fast-growing sectors doesn’t support.

The rebuttal to these concerns isn’t that they’re wrong, it’s that they’re already partially priced into the current state of the field. School lunch plant-based programs expanding across California and New York reflects an environment where participants are already adapting to constraints rather than operating in an unconstrained space. The adjustment capacity of the ecosystem is higher than a purely top-down view of the risks suggests.

Looking Forward

The trajectory here is clearer than the pace. Making predictions about when specific thresholds will be crossed is genuinely difficult, and anyone claiming precision about timelines should be treated with skepticism. But the direction, toward Beyond Meat and Impossible Foods revenue declining and continued development of the conditions described above, is supported by the evidence in a way that doesn’t depend on a single variable going right.

School lunch plant-based programs expanding across California and New York is the variable to watch as the leading indicator. Historical patterns suggest it moves first, with broader metrics following with some lag. This doesn’t make the outcome certain, but it makes it readable, and readability is the precondition for good decisions.

Three questions are worth holding as the story develops. First: are the structural conditions that enabled the current state durable, or are they cyclical? Second: who’s positioned to benefit from the next phase, and does that differ materially from who benefited in the current phase? Third: what would a clean falsification of the optimistic thesis look like, and is there any evidence of that signal emerging? These questions don’t need answers today, but having asked them changes what you notice in the months ahead.

The analysis holds up under scrutiny, which is the only test that matters. The current moment in plant-based food evolution past the hype is one where the people who have built an accurate model of the underlying dynamics are better positioned than the people who are relying on the surface story. Building that model isn’t a quick task, but it’s doable, and this analysis is intended as one input into it.

What’s peak where you are right now?

Sake2me

Sake2me

Food writing that goes beyond the recipe.

Food is culture, memory, science, and pleasure. We write about all of it. Recipes developed through real testing in actual kitchens. Restaurant criticism that takes the work seriously. Deep dives into ingredients and techniques that make you think differently about cooking.

Topics we cover: Recipes · Restaurant Reviews · Technique · Ingredients · Food Culture · Travel

What Seasonal and local food advocacy Reveals About Plant-based food evolution past the hype

The evidence, when you look closely, tells a more specific story. Plant-based food evolution past the hype deserves better analysis than the surface-level coverage it usually gets. The reason becomes clear once you know where to look.

What matters isn’t the headline number. When you view it through seasonal and local food advocacy, you see whole food plant-based eating growing while ultra-processed alternatives plateau. This grounded reading is also more accurate once you examine what the evidence actually shows.

What Seasonal and local food advocacy Reveals About Plant-based food evolution past the hype

The Advocacy: Setting the Terms

Beyond Meat and Impossible Foods revenue declining after their pandemic peak isn’t just another data point in plant-based food evolution. It’s the structural condition that makes everything else in this analysis make sense. This context has staying power. The conditions creating it have been building for years, and their convergence makes this moment different from previous ones that looked similar from afar.

Whole food plant-based eating is growing while ultra-processed alternatives plateau. Tempeh, jackfruit, and legume-forward menus are replacing meat analogues in fine dining. Look at both trends together and a pattern emerges that Good Food Institute research has been tracking from the inside. The conditions are more durable than they first appear, and the implications reach further than the immediate headlines suggest.

To understand why this matters, compare what was true three years ago to what’s true now. The change isn’t just quantitative, it’s qualitative. The participants, infrastructure, and incentive structures have all shifted in ways that build on each other rather than cancel out. That compounding effect is what’s most important to track.

What makes this moment worth careful examination isn’t its novelty but its confirmation. The underlying dynamics have been visible for some time. What’s new is that they’ve reached a threshold where ignoring them requires active effort rather than simple inattention. That threshold crossing is the real event, not the underlying movement that produced it.

The flexitarian category is now the largest dietary identity in the US at 36 percent. This is part of the same picture. These elements don’t exist in separate silos, they’re reinforcing conditions in the same structural shift.

Illustration for What Seasonal and local food advocacy Reveals About Plant-based food evolution past the hype

The Seasonal Argument: The Analysis

That 36 percent flexitarian statistic is where the analysis gets more specific. The surface reading is accessible and not wrong, but it misses the mechanism. The mechanism is where the practical insight lives. What matters isn’t the headline number but the mechanism behind it: precision fermentation enabling animal-free dairy proteins at competitive cost. Understanding this changes what you do with the information.

Consider what precision fermentation enabling animal-free dairy proteins at competitive cost represents in context. This isn’t a correlation that happened to appear. It’s a downstream consequence of structural factors that have been building. Previous readings of similar situations failed because they treated the symptom as the cause. The structural account is less satisfying as a headline but more useful as an analytical tool.

The comparison to prior cycles is instructive precisely because of where it breaks down. Superficially similar conditions resolved differently in previous iterations because the substrate was different. What school lunch plant-based programs expanding across California and New York represents is a substrate change, the kind that alters the elasticity of the system rather than just its current value. Recognizing that distinction separates analysis from pattern-matching.

The skeptical counterargument deserves honest engagement: prior moments with similar surface characteristics didn’t produce the outcomes that seemed logical at the time. That history is real. What’s different now is school lunch plant-based programs expanding across California and New York, which isn’t a minor variable. It’s the infrastructure condition that previous cycles lacked. Infrastructure changes tend to persist in ways that sentiment-driven changes don’t. Food Navigator plant-based is one source tracking this dimension with the rigor it requires.

There’s also a distributional question that often goes unaddressed in coverage of plant-based food evolution past the hype: who captures the value created by these shifts, and who absorbs the disruption costs? The aggregate picture can be positive while the distribution is uneven in ways that matter enormously to specific participants. Keeping that distributional lens in view is part of reading the situation clearly rather than simply optimistically.

Implications: What This Means If You Care About Seasonal eating

The implications of plant-based food evolution past the hype extend beyond the immediate context. Beyond Meat and Impossible Foods revenue declining after their pandemic peak, combined with the structural conditions described above, creates a situation where adjacent fields, decisions, and communities are affected in ways that aren’t always visible from inside the primary story. The second-order effects are frequently more important than the first-order ones, and they’re where careful attention pays the highest returns.

The frame that matters here, and this is where the analysis departs from mainstream coverage, is that tempeh, jackfruit, and legume-forward menus replacing meat analogues in fine dining is a leading indicator rather than a lagging one. The people positioned to respond to what this signals, rather than to what it confirms, are the ones who will be less surprised by what follows.

The practical response depends heavily on your position relative to the dynamics at play. For those closest to the core of plant-based food evolution past the hype, the implications are immediate and operational. For those at greater distance, the implications are strategic, a matter of understanding which adjacent pressures are building and which assumed stabilities are more fragile than they appear.

The practical question isn’t whether to engage with these dynamics but how. The answer depends on context, on what role you occupy relative to plant-based food evolution past the hype and what your actual decision horizon is. But the first step is the same regardless: accurate understanding of what’s actually happening rather than what the most available narrative says is happening.

A few concrete observations are worth separating out from the broader analysis. First: whole food plant-based eating growing while ultra-processed alternatives plateau isn’t a temporary condition, it’s a new baseline. Second: precision fermentation enabling animal-free dairy proteins at competitive cost suggests that the adjustment period isn’t over. Third, and most important: the organizations and individuals who are treating the current moment as a new steady state rather than a transition are making a categorization error that will be costly to unwind later.

The Case Against: What the Critics Get Right

Intellectual honesty requires acknowledging the strongest counterarguments, not just the weakest ones. The case against the optimistic reading of plant-based food evolution past the hype isn’t trivial. There are structural vulnerabilities in the current picture that deserve direct engagement rather than dismissal.

The most serious objection is about sustainability. Tempeh, jackfruit, and legume-forward menus replacing meat analogues in fine dining can be read not as a foundation but as a ceiling, a point beyond which growth becomes self-limiting because of the very dynamics that produced it. If the current state has already incorporated most of the available supply of early-adopting participants, the remaining growth curve may be structurally shallower than the recent trajectory implies.

There’s also the policy and regulatory dimension. Beyond Meat and Impossible Foods revenue declining after their pandemic peak describes a condition in a relatively permissive environment. Regulatory responses to the scale implied by these numbers aren’t inevitable, but they aren’t implausible either. Organizations planning as though the current regulatory environment is permanent are making an assumption that the history of fast-growing sectors doesn’t support.

The rebuttal to these concerns isn’t that they’re wrong, it’s that they’re already partially priced into the current state of the field. School lunch plant-based programs expanding across California and New York reflects an environment where participants are already adapting to constraints rather than operating in unconstrained space. The adjustment capacity of the ecosystem is higher than a purely top-down view of the risks suggests.

Looking Forward

The trajectory here is clearer than the pace. Making predictions about when specific thresholds will be crossed is genuinely difficult, and anyone claiming precision about timelines should be treated with skepticism. But the direction, toward Beyond Meat and Impossible Foods revenue declining further and continued development of the conditions described above, is supported by evidence in a way that doesn’t depend on a single variable going right.

School lunch plant-based programs expanding across California and New York is the variable to watch as the leading indicator. Historical patterns suggest it moves first, with broader metrics following with some lag. This doesn’t make the outcome certain, but it makes it readable, and readability is the precondition for good decisions.

Three questions are worth holding as the story develops. First: are the structural conditions that enabled the current state durable, or are they cyclical? Second: who is positioned to benefit from the next phase, and does that differ materially from who benefited in the current phase? Third: what would a clean falsification of the optimistic thesis look like, and is there any evidence of that signal emerging? These questions don’t need answers today, but having asked them changes what you notice in the months ahead.

The analysis holds up under scrutiny, which is the only test that matters. The current moment in plant-based food evolution past the hype is one where people who have built an accurate model of the underlying dynamics are better positioned than those relying on the surface story. Building that model isn’t a quick task, but it’s a tractable one, and this analysis is intended as one input into it.

What’s peak where you are right now?